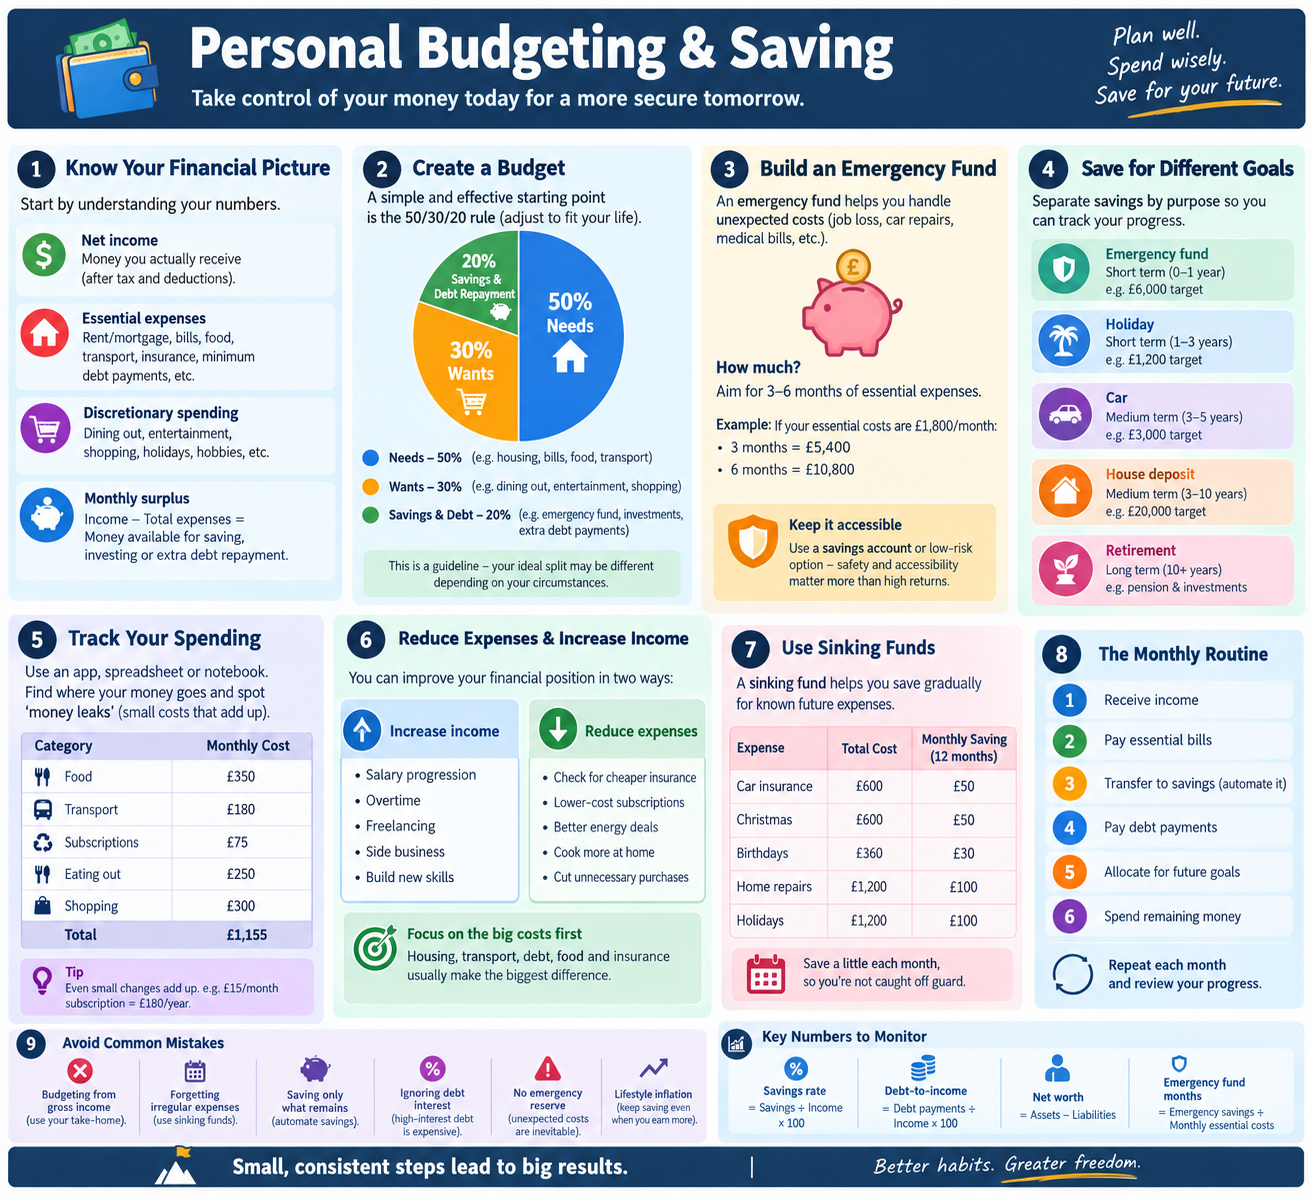
Personal Budgeting & Saving
Personal budgeting is the process of deciding where your money should go before you spend it. Saving is the process of deliberately keeping part of your income for future needs and goals.
The overall system is:
Earn → Budget → Spend → Save → Protect → Invest
1. Start with your financial picture
Before making a budget, calculate four numbers:
Monthly net income
The money that actually reaches your account after tax and other deductions.
Include:
- Salary
- Self-employment income
- Benefits, where applicable
- Regular freelance income
- Other reliable income
Don’t rely on uncertain income when planning essential expenses.
Monthly essential expenses
Examples:
- Rent/mortgage
- Council tax
- Utilities
- Food
- Transport
- Insurance
- Minimum debt payments
- Essential childcare
Monthly discretionary spending
Examples:
- Restaurants
- Entertainment
- Shopping
- Holidays
- Hobbies
- Subscriptions
Monthly saving/debt reduction
This is what you’re deliberately allocating toward your future.
A basic calculation is:
If income is £3,000 and expenses are £2,400:
You have £600 available for saving, investing, additional debt repayment, or other goals.
Build a simple budget
A useful starting framework is the 50/30/20 rule:
- 50% → needs
- 30% → wants
- 20% → saving/debt repayment
But treat this as a framework, not a law.
Someone living in an expensive area might need considerably more than 50% for housing. Someone aggressively paying off debt might allocate much more than 20% toward financial goals.
The best budget is one that reflects your actual circumstances.
. Use three categories
For simplicity, divide spending into:
Needs
Things you genuinely need.
Wants
Things that improve your lifestyle but aren’t essential.
Future you
Money allocated to:
- Emergency savings
- Debt repayment
- Pension
- Investments
- Major future purchases
This third category is important because saving shouldn’t be treated as merely “whatever happens to be left.”
Pay yourself first.
Automate saving
One of the easiest ways to save consistently is automation.
For example:
Salary arrives → automatic transfer → savings account
rather than:
Salary arrives → spend → save whatever remains
Suppose you receive £2,500 per month.
You could automatically transfer £300 to savings shortly after payday.
Over 12 months:
That’s £3,600 saved without requiring a decision every month.
Create an emergency fund
An emergency fund is money specifically reserved for unexpected financial problems.
Examples:
- Losing your job
- Major car repair
- Emergency travel
- Unexpected household expense
- Essential replacement purchase
The appropriate size depends on your circumstances.
Consider:
- Job stability
- Dependants
- Housing costs
- Insurance
- Health-related costs
- Debt
- Whether you’re self-employed
. Keep emergency money accessible
Emergency savings generally shouldn’t be placed somewhere where you could lose a large portion of the money when you need it.
For money needed in the short term, people commonly consider savings accounts or other low-risk, accessible arrangements.
The objective isn’t maximum investment return.
It’s:
Safety + accessibility + reasonable interest
Separate savings by purpose
Instead of having one giant savings balance, you can create different goals.
For example:
| Goal | Target | Monthly saving |
|---|---|---|
| Emergency fund | £6,000 | £300 |
| Holiday | £1,200 | £100 |
| Car | £3,000 | £150 |
| House deposit | £20,000 | £250 |
This makes your progress much easier to understand
Use sinking funds
A sinking fund is money gradually saved for a known future expense.
Suppose you know you’ll need £600 for car insurance in 12 months.
Instead of finding £600 suddenly:
Save £50 each month.
Other sinking funds might cover:
- Christmas
- Birthdays
- Holidays
- Car maintenance
- Annual insurance
- School expenses
- Home repairs
This prevents predictable expenses from becoming financial emergencies.
. Track your spending
You can’t manage what you don’t understand.
For one month, record every expense.
You might discover:
Food: £350
Transport: £180
Subscriptions: £75
Eating out: £250
Shopping: £300
The purpose isn’t to feel guilty about spending.
It’s to identify where your money is actually going.
Find your “money leaks”
Small recurring expenses can add up.
For example:
£15 subscription × 12 = £180/year
£40/month takeaway spending = £480/year
£75/month impulse purchases = £900/year
Individually these may seem insignificant. Collectively they can materially affect your savings rate.
But don’t try to eliminate every enjoyable expense.
A sustainable budget should leave room for enjoyment
Tinggalkan Balasan